
Mortgage Affordability Calculator Hampton, VA
How much house can you afford in Hampton? See your maximum price, monthly payment and pre-approval estimate. Free, instant, no credit check.
Updated · current rates and lending limits
Add your partner's income if you're buying together.
Car loans, credit cards, lines of credit, student loans. Not rent.
Enter your yearly household income.
Savings and gifts from family count. Many first-time buyer loans need just 3% down; under 20% you pay mortgage insurance.
7.40% (Freddie Mac 30-year average, October 2026). Change it if you've been quoted a rate.
Enter your down payment.
| After | Paid in total | Still owed |
|---|
 OneMain Financial
4.3 · 45 reviews · Free pre-approval
Get pre-approved →
 OneMain Financial
4.5 · 40 reviews · Free pre-approval
Get pre-approved →
 Old Point Mortgage
5.0 · 9 reviews · Free pre-approval
Get pre-approved →
An estimate, not a mortgage approval or pre-approval. A mortgage broker confirms your real number.
Top-rated mortgage brokers in Hampton
Ranked by TrustAnalytica from verified reviews · see the full Top 10 list →
OneMain Financial
OneMain Financial focuses on personalized lending that considers individual needs beyond credit scores, offering personal loans, credit cards, and mortgage payment solutions. Customers appreciate the professional and patient support from the team, though some have noted discrepancies in payoff amounts. The company provides clear terms and in-person guidance through its branch network.
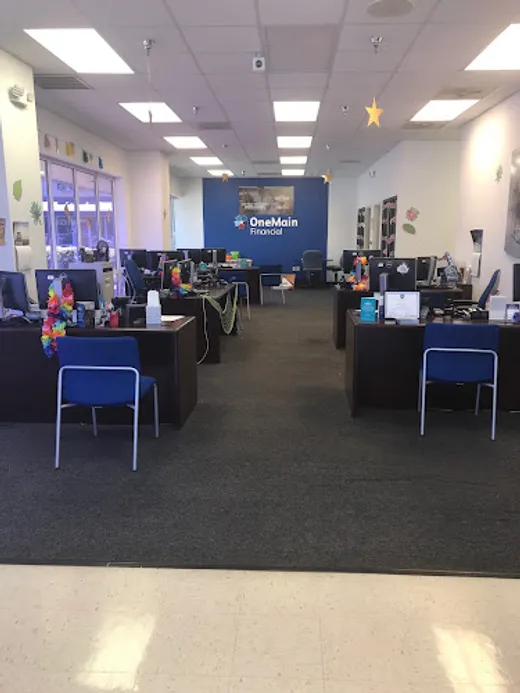
OneMain Financial
OneMain Financial specializes in providing personal and business loans with a straightforward application process. The team assists clients through each step, often making the experience smooth and clear. Some customers note the process can take time, but overall find the support helpful.
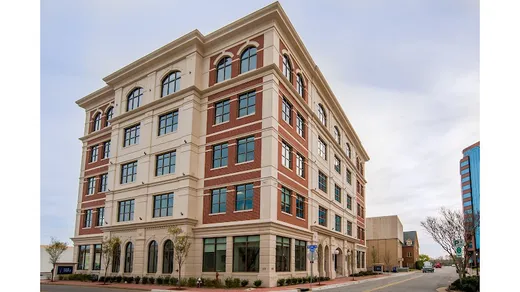
Old Point Mortgage
Old Point Mortgage offers personalized refinancing and mortgage services with a focus on clear communication and helpful support. The team works closely with clients and partner organizations to navigate the home financing process. Customers appreciate the attentive assistance, though experiences may vary depending on individual interactions.
Sherry Thacker SVP | Mortgage Loan Officer with TowneBank Mortgage
TowneBank Mortgage offers personalized mortgage lending with a focus on attentive service and clear communication. The team handles a range of loan options, guiding clients through the process with professionalism and care. Customers appreciate their positive approach and attention to important details throughout each transaction.
Hampton Mortgage Statistics
Home-purchase lending in Hampton City County and home costs in Hampton, VA (latest HMDA and Census data)Lenders made 1,897 home-purchase loans in Hampton City County in 2025 (average about $282,000) and denied 207 — 10% of decided applications, compared with 11% across Virginia, according to federal mortgage data (HMDA, CFPB). In Hampton, the median home is worth $245,700 and 71% of owners have a mortgage, paying a median $1,704 a month (Census ACS 2020–2024).
- Home-purchase loans, 2025
- 1,8970%1,891 in 2024
- Denial rate
- 10%VA 11%
- Median home value
- $245,700VA $383,700
- Monthly cost with a mortgage
- $1,704median · VA $2,127
- Refinance loans made (Hampton City County, 2025)
- 1,232 · 955 in 2024
- Home-improvement loans made (2025)
- 354
- Average home-purchase loan
- $282,000 (VA $452,000)
- Owners with a mortgage
- 71% · 34% of them spend 30%+ of income on housing
- Median household income
- $69,621 (VA $93,170)
Source: CFPB / FFIEC Home Mortgage Disclosure Act (HMDA) data, 2024–2025 loan applications in Hampton City County (originated vs denied); home values and costs: U.S. Census Bureau ACS 2020–2024. Compiled by TrustAnalytica.
How this Hampton mortgage affordability calculator works
Lenders look at your debt-to-income ratio. Housing costs (principal and interest, property tax, homeowners insurance and mortgage insurance) should stay under about 31% of your gross monthly income, and housing plus your other monthly debts under 43%. The calculator finds the highest home price that passes both tests with your down payment, on a 30-year fixed loan.
Virginia rules and numbers this calculator uses
- Debt-to-income
- 31% for housing and 43% total, the FHA standard and the long-time Qualified Mortgage limit. Some conventional loans go higher with strong credit and savings.
- Down payment
- At least 3% on a conventional first-time buyer loan (3.5% on FHA). Under 20% down, private mortgage insurance of about 0.6% of the loan a year is added to the payment.
- Property tax
- About 0.75% of the home's value a year, the Virginia average for owner-occupied homes (2024 Census ACS).
- Insurance
- Homeowners insurance assumed at $150 a month; it varies a lot by home and location.
- Rate
- Starts at 7.40% (Freddie Mac 30-year average, October 2026). Change it to the rate you have been quoted.
An estimate, not a mortgage approval or pre-approval. Your credit, income type, the property and the lender all change the answer; a mortgage broker confirms your real number. Sources: Freddie Mac Primary Mortgage Market Survey (October 2026), U.S. Census Bureau American Community Survey 2024 property tax data, FHA and CFPB debt-to-income guidance.
Frequently asked questions
10 questionsHow does the mortgage affordability calculator work?
How accurate is the mortgage affordability calculator for Hampton?
What is the debt-to-income ratio limit for mortgages in Virginia?
What is the minimum down payment for a first-time buyer in Virginia?
How does PMI affect my mortgage in Hampton?
How do interest rates impact mortgage affordability in Virginia?
How do existing debts affect my mortgage eligibility in Hampton?
What are property tax rates for homes in Virginia?
What's the difference between mortgage pre-approval and pre-qualification?
What role does a mortgage broker play in Hampton?
General information, not financial advice — consult a qualified professional.